Veterans
How Do You Get Pre-Approved for a VA Loan in Houston?
To get pre-approved for a VA loan, you pick a VA-approved lender, send them your income, asset and military service documents, and let them pull your credit and your Certificate of Eligibility. The lender reviews all of it and gives you a written letter stating how much you can borrow. In Houston that usually takes a few days to about a week once your paperwork is in, and it should happen before you tour a single home.
The Move Live Love TX Team™ is a husband-and-wife real estate team serving Houston and the surrounding areas, helping veterans and military families buy with a VA loan, with a certified Military Relocation Professional on every deal.
The five steps, in order
- Confirm you meet the service requirement. Most veterans and active-duty members do. The details are below.
- Choose a lender that closes VA loans every month. Any lender can offer one. Fewer know the program well.
- Send your documents. Income, bank statements and proof of service.
- Let the lender pull your credit and your Certificate of Eligibility. You authorize both. They do the work.
- Get the letter. It names a loan amount and goes with every offer you write.
That’s the whole process. The rest of this page is what each step asks of you.
Do you qualify in the first place?
The VA sets the service requirement, and it depends on when and how you served. As of October 2026, VA.gov’s eligibility page lists these as the most common paths:
- On active duty now: at least 90 continuous days of service.
- Veteran who served after August 2, 1990: 24 continuous months, or the full period you were called to active duty, as long as that was at least 90 days.
- National Guard or Reserve: six creditable years, or 90 days of active-duty service that wasn’t for training.
A discharge for a service-connected disability can qualify you with less time. Guard and Reserve rules have more wrinkles than this, and we walk through them in National Guard and Reserve VA loan eligibility in Houston.
Pre-qualified and pre-approved mean different things
A pre-qualification is a lender’s estimate based on numbers you tell them over the phone. Nobody checks anything. It takes a few minutes.
A pre-approval means the lender has your documents, has pulled your credit, and has confirmed your eligibility. Listing agents in Houston know the difference, and an offer backed only by a pre-qualification is easy for a seller to pass over.
So ask your loan officer one question. “Has an underwriter looked at my file, or only you?” Some lenders will send the file through underwriting before you’ve found a house. That is the strongest letter you can carry.
The paperwork, by where you are in your service
Proof of service is the part that trips people up, because it changes with your status. VA.gov lists what each person needs:
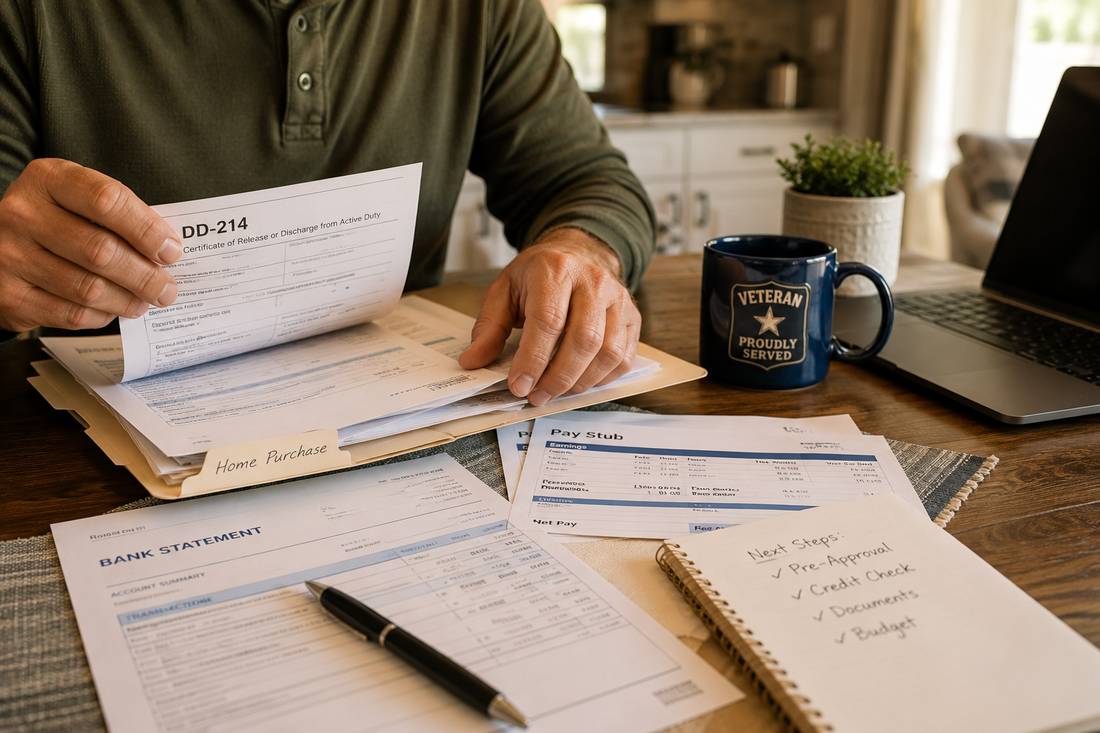
- Veteran: a copy of your DD214.
- Active duty: a statement of service signed by your commander, adjutant or personnel officer. It has to show your full name, Social Security number, date of birth, the date you entered duty, any lost time, and the name of your command.
- Guard or Reserve, never activated: a signed statement of service that also shows your total creditable years.
- Surviving spouse: the veteran’s DD214 if you have it, plus the VA form that matches your situation. Your lender will tell you which one.
For income, plan on your most recent pay stubs or Leave and Earnings Statement and two years of W-2s or tax returns. If you receive disability compensation or military retirement, add the award letter. Housing allowance counts as income too, and how lenders treat BAH on a VA loan explains how.
For assets, two to three months of bank statements. A VA loan doesn’t require a down payment in most cases, but the lender still wants to see you can cover closing costs and have something left over.
Your Certificate of Eligibility
The Certificate of Eligibility, or COE, is the VA’s confirmation that you’ve earned the benefit and how much entitlement you have. VA.gov gives three ways to request it: online, through your lender, or by mailing VA Form 26-1880 to your regional loan center. The VA says mail takes longer.
I’d let the lender pull it. They do this every day, and it keeps your file in one place.
One thing buyers get wrong here. A COE is not a pre-approval. The VA says so directly: even with full entitlement, your lender still has to approve you for the loan.
What decides the number on your letter
The VA doesn’t set your loan amount. The lender does, and VA.gov names the four things they weigh: your credit history, your income, your debts and your assets.
Two parts of that are particular to VA loans. The first is residual income, which is the money left each month after your major bills are paid. A VA lender has to check it, and it can carry a file that looks tight on debt alone. We cover the numbers in the VA residual income requirement. The second is entitlement. If you’ve used a VA loan before and still own that home, your remaining entitlement can change how much you can borrow with nothing down.
Credit score is the lender’s call, so the minimum changes from one lender to the next. That alone is a reason to talk to more than one, and what credit score veterans need in Houston shows the range.
Then there’s the piece that surprises Houston buyers more than it should. Your letter is built on an estimated monthly payment, and that estimate includes property taxes and insurance. Around Houston, two homes at the same price can carry different payments, because the tax rate changes with the county, the school district and whether the neighborhood sits in a municipal utility district. Flood insurance depends on the lot. A letter written around one tax rate can come up short on a house in a higher-rate community.
Ask your lender what tax rate they assumed. Then ask them to run it again at the rate for the area you’re shopping. If you have a VA disability rating, tell them that too, because Texas property tax exemptions for veterans can lower the payment.
The VA funding fee belongs in the same conversation. With less than 5% down it is 2.15% of the loan on your first use and 3.3% after that, under the rates VA.gov shows as effective April 7, 2023. You can pay it at closing or roll it into the loan. If you receive VA compensation for a service-connected disability, you don’t pay the funding fee at all.
How long it takes, and how long it lasts
A few days to about a week, when the lender has everything. The slow part is almost never the lender. It’s the tax return from two years ago, or the statement of service waiting on a signature.
Most letters are good for 60 to 90 days, and that varies by lender. If your search runs longer, the lender refreshes it with new pay stubs and bank statements. You don’t start over.
Between the letter and the closing table
The lender checks your credit and your job again before closing. So from the day you’re pre-approved until the day you get keys, leave your finances alone. Don’t finance a truck. Don’t open a store card for the furniture. If a job change or new orders are coming, tell your loan officer before it happens, not after.
This is the most common way a solid approval falls apart, and it’s avoidable every time.
What we’d do if this were our file
Gather the documents before you call anyone. It turns a two-week back-and-forth into a few days.
Talk to two lenders who close VA loans all the time, and compare more than the rate. How to choose a VA lender in Houston has the questions we’d ask.
And when you write an offer, have the lender issue a letter for that offer’s price. Your full approval amount is your business. The seller doesn’t need to see it.
Vicky holds the Military Relocation Professional designation, which is training specific to military moves and VA financing. On a PCS clock, a slow pre-approval can cost you the house, so this is the first thing she sorts out with a military family.
When you’re ready for what comes after the letter, everything a veteran needs to buy a home in Houston lays out the full path, and our VA Home Buying Guide is free, and yours to keep.
Frequently Asked Questions
- How do you get pre-approved for a VA loan?
- You choose a VA-approved lender, give them your income, asset and military service documents, and authorize a credit check. The lender confirms your Certificate of Eligibility, reviews the file, and issues a written letter stating how much you can borrow.
- What documents do you need for VA loan pre-approval?
- Most lenders ask for recent pay stubs, two years of W-2s or tax returns, two to three months of bank statements, and proof of service. Proof of service is a DD214 for a veteran or a signed statement of service for someone on active duty.
- Do you need a Certificate of Eligibility before you apply for pre-approval?
- No. You can request your Certificate of Eligibility yourself on VA.gov, but most lenders can request it for you through the VA's system while they review the rest of your file. Asking the lender to pull it is usually the faster route.
- How long does VA loan pre-approval take in Houston?
- Most VA pre-approvals take a few days to about a week once the lender has every document. The delay is almost always a missing document, such as an old tax return or a statement of service that still needs a signature.
- What's the difference between VA pre-qualification and pre-approval?
- Pre-qualification is an estimate based on numbers you report yourself, with nothing verified. Pre-approval means the lender has reviewed your documents, pulled your credit and confirmed your eligibility, so the letter holds up when a seller's agent reads it.
- How long is a VA pre-approval letter good for?
- Most VA pre-approval letters are good for 60 to 90 days, depending on the lender. If your search runs longer, the lender can usually refresh the letter with updated pay stubs and bank statements, without starting over.
- Can you get pre-approved for a VA loan with no down payment?
- Yes, in most cases. The VA says its guaranty lets an eligible buyer with full entitlement purchase with no down payment, as long as the lender approves the loan. The lender still decides the amount from your credit, income, debts and assets.
